
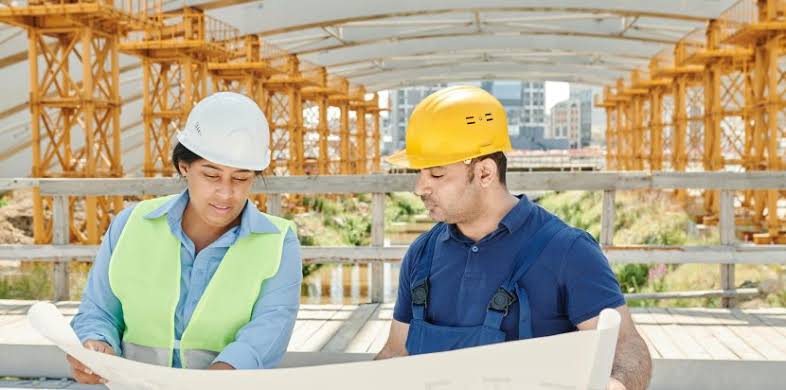
Construction service providers do more than just finish projects on time and within budget. Unpredictable occurrences, injury to employees, loss of equipment, property damage, and accidents can all turn into quick troubles for contractors. These risks can be addressed through a structured approach to risk management, such as insurance, improving the contractor’s ability to safeguard their business, and increasing the level of confidence across the project lifecycle.
Why Contractors Need Insurance?
Each building endeavor has its own possible risk factors. In the construction process, there is a potential for a worker to be injured, equipment to be damaged, or a client’s property to be accidentally damaged. Incidents, no matter how trivial, can lead to repair expenses, legal fees or claims for compensation.
Through insurance, the contractor may have some of these financial risks shifted to the insurance company for a price, where legal limits, conditions and exclusions apply. Coverage depends on the trade, business structures, employees, equipment, vehicles and types of projects that the contractor performs.
Different Types of Contractor Coverage
- One of the most common types of insurance coverage for contractors is general liability insurance. It may also be used to settle some third-party bodily injuries or property damage claims related to business operations.
- Commercial auto insurance might also be applicable where a contractor uses cars to move employees, equipment or construction materials. Equipment and tool insurance can be especially beneficial for companies that frequently transport valuable equipment and tools from one job site to the next.
- An additional factor for qualifying businesses that have staff members would be Workers’ compensation. It can help employers comply with relevant legislation and also offer advantages to employee injuries that occur in their workplaces.
Specific and specialized areas may also require contractors to have professional liability, builders’ risk or other coverage. This will ensure your prospective clients are covered at an appropriate level of risk. When investigating contractor insurance San Antonio options, a business should determine its own business activities first, before deciding which policy it needs to purchase that does not have too few provisions.
A roofing company, for instance, might have unique exposures from an electrical or an interior improvement business. Insurance requirements also can be determined by contracts. Specific coverage insurance or certificates of insurance might be necessary before work commences, and they could be asked by clients, property owners and general contractors. These requirements must be considered early to avoid duplication of efforts and to avoid delays.
Highlighting Emerging Risks in Construction
As the construction industry continues to change, so will the things contractors should keep in mind. Expanding equipment expenses, supply chain disruption, more complicated projects, vehicle risks, and growing reliance on subcontractors have all the ability to influence the way that businesses go about risk management.
Using digital project management systems, tracking equipment use, monitoring safety, and keeping electronic records can help contractors identify issues and keep track of documentation. Technology is no substitute for risk but can help reinforce good prevention and documentation.
Confirmed Approach to Risk Management
Risk management activities increase the value of insurance. Some steps contractors can take to reduce their exposure include: keeping equipment in top condition, training employees on safety procedures, documenting safety procedures, ensuring that subcontractors have coverage, and carefully reviewing the contract before beginning projects. Policies and procedures need to be updated periodically, particularly in the event of new equipment being bought, new staff being hired, new services being introduced, or the company’s work base expanding even more.
Conclusion
In the end, contractor insurance San Antonio is just a piece of the puzzle when it comes to safeguarding a construction firm and addressing financial uncertainties. With knowledge of their exposures, a review of contractual obligations and coverage to match their actual operations, contractors can build a stronger foundation for projects and ensure the long-term viability of their businesses.